A Household Bill Calendar helps you see recurring bills, paydays, and automatic payments in one clear checklist so you can track due dates and utility costs with less stress. It outlines practical steps for organizing billing accounts while reminding you to confirm current rules and seek professional tax or legal advice.
What a Household Bill Calendar Does and Why It Matters
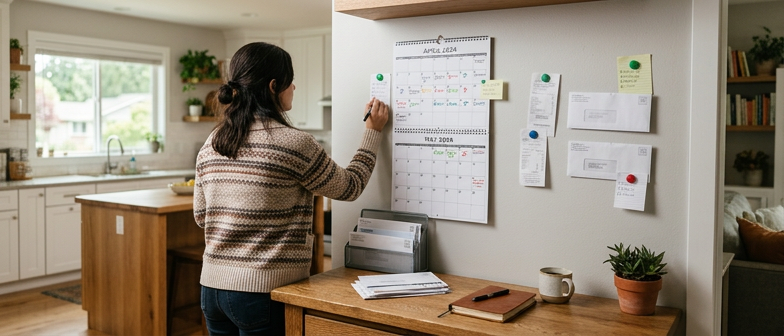
A Household Bill Calendar is a simple way to see your regular bills and payments mapped across the month, matched to when income actually arrives. Instead of keeping separate notes for rent, utilities, insurance, and subscriptions, this calendar gathers everything in one place and works as a monthly payment checklist you can scan quickly. You list each bill, its usual amount, and the due date, then compare that schedule to paydays and other cash inflows. This overview does not replace a full budget, but it supports one by helping you notice tight weeks, avoid missed payments, and plan for recurring obligations in a clearer, lower‑stress format.
Due date tracking is the core job of a bill calendar, because late payments can lead to fees, service interruptions, or credit impacts. By marking dates and reviewing any automatic payments, you can decide which bills to pay right after you are paid and which can wait until later in the month, making sure they line up with your expected balance. The calendar also gives you space to note changes such as seasonal utility costs or new service fees, and to keep billing accounts organized alongside your broader spending plan. Because rules, fees, and consumer protections can change, confirm current terms with your providers and seek qualified financial, tax, or legal advice for personalized guidance instead of treating a bill calendar as professional recommendations.
Building a Clear Recurring Bill List
A clear recurring bill list is the backbone of a household bill calendar because it shows every regular obligation in one place. Start by reviewing recent bank and credit card statements to capture fixed charges such as rent or mortgage, utilities, phone and internet, insurance premiums, streaming services, and any automatic memberships or subscriptions. Then add flexible but predictable items like usual grocery spending or transportation costs if you want a fuller view of the month. For each bill, record the service name, billing account details, the typical amount, and how you pay it, whether by online payment, paper check, or automatic debit. Putting this information into one document or spreadsheet supports better billing account organization and shows the commitments that compete for your income before you make everyday spending decisions.
Once your recurring obligations are listed, connect them to your cash flow with a simple monthly payment checklist that fits your pay schedule. Group bills by due date and by which account they use so you can match them to the paychecks or deposits that arrive just before those dates. Highlight which obligations are on autopay and which need manual review, so you check statements for accuracy and confirm balances and available funds. You can also sort items by type, such as housing, utilities, insurance, and subscriptions, to see what could be adjusted if money gets tight. Because terms and fees change, revisit this list regularly and verify current conditions with each provider, and seek qualified financial or legal advice if you have questions about how payment choices affect your credit, taxes, or consumer rights.
| Bill Category | Key Details to Record | Payment Method Focus | Cash Flow Impact | Review Reminder |
|---|---|---|---|---|
| Housing (rent or mortgage) | Service name, due date, account reference | Manual pay or scheduled online transfer | High impact on monthly cash available | Confirm timing and terms with provider regularly |
| Utilities (electricity, gas, water, internet) | Billing period, typical amount, account login | Autopay or online bill pay setup | Moderate impact with seasonal variation | Check statements and verify current rates |
| Insurance premiums | Policy type, renewal cycle, payment source | Automatic debit or card charge | Ongoing protection, medium payment priority | Review coverage and fees with licensed professional |
| Subscriptions and memberships | Service list, renewal dates, cancellation steps | Autopay on card or payment app | Low to medium impact on cash flow | Audit charges and adjust if budget is tight |
| Groceries and transportation | Usual pattern, primary card or account | Point-of-sale or recurring refill charges | Flexible spending tied to income timing | Revisit estimates and align with current expenses |
Organizing Accounts and Billing Details
A simple system for organizing billing accounts keeps your Household Bill Calendar accurate over time. Store key details for each bill in one secure place, such as the company name, account number, website, and customer service phone line. You can use a password manager or digital document, or a paper binder in a safe spot, as long as you can quickly review information when a due date changes, a statement looks unusual, or you switch providers.
To keep Billing Account Organization practical, link each account entry to the calendar itself. Note the usual due date, how statements arrive, and whether you pay manually or through automatic payments. Add short notes on utility costs and recent fee changes so shifting amounts are easy to understand and your Monthly Payment Checklist stays current. Because rules and policies change, confirm details with providers and seek professional advice for tax or legal questions.
Tracking Due Dates and Payment Methods
A household bill calendar is most useful when it clearly shows when each bill is due and how it will be paid. List every recurring bill, such as rent or mortgage, utilities, insurance, and subscriptions, and note the due date from each statement. Compare those dates with your paydays so you can see which bills each paycheck covers and where cash flow might be tight. Turn this into a simple monthly payment checklist, marking bills when they are scheduled and again when they are confirmed as paid, whether you keep it in a notebook, spreadsheet, or a calendar tool you already use.
Once all due dates are visible in one place, decide which bills you will handle manually and which you are comfortable automating. Manual payments offer more control and a quick review of each bill, but they require close attention to due date tracking so you do not miss a payment window. Automatic payments help prevent forgotten bills, yet they work best when you review them regularly to confirm the amount, timing, and account being used. A brief automatic payment review each month, tied to your bill calendar, helps you spot changes in rates, fees, or billing cycles and adjust if your income or expenses shift.
As you refine your system, aim for a balance between convenience and oversight. You might automate fixed, predictable bills while paying variable expenses like changing utility costs or usage based services more directly so you can notice patterns and adjust your budget. Your household bill calendar should show upcoming payments at least a couple of weeks ahead and remind you when to move money or update settings, instead of only recording past activity. Because rules for billing, overdraft fees, and payment processing can change, confirm current terms with your providers and consult a qualified financial or legal professional if you have questions about contracts or consumer protections.
Reviewing Automatic Payments Safely
Within a household bill calendar, automatic payments can simplify due date tracking because recurring withdrawals follow a set schedule. To keep that convenience from leading to overdraft fees or missed bills, review each automatic charge against the due dates in your calendar and your recurring bill list at least once a month. Confirm the amount, timing, and which checking or savings account is used so you see how every bill affects your cash flow.
Safe automatic payment review also means scanning bank statements and alerts for changes, such as higher utility costs or a subscription you did not approve. If something looks wrong, contact the provider or your financial institution quickly and ask about their dispute and cancellation rules and deadlines. Because account terms and protections change, verify current policies with your bank, card issuer, or service provider, and consider a qualified professional for personal legal or tax guidance.
Adding Utility Cost Notes and Seasonal Patterns
As you refine your Household Bill Calendar, add short notes to each utility entry so you can see how costs change through the year. Next to electricity, gas, water, internet, and other services, record the amount, the billing period, and any detail that explains a higher or lower bill, such as unusual weather, guests, or a rate change from your provider. Over time, these utility cost notes turn the calendar from a simple due date tool into a basic record of household usage. Looking back, you can spot recurring peaks, odd spikes, and months when your utilities tend to be lighter, all within one organized view of your regular expenses.
After you have at least a few seasons of notes on your Household Bill Calendar, you can use those patterns to plan more realistic monthly spending without assuming guaranteed savings. Seeing that winter heating or summer cooling usually raises your totals can help you set aside extra funds in those months and adjust other flexible expenses. Many people also add a reminder to review utility accounts annually, check for updated rate structures, or consider conservation steps that fit their situation. Because rates, programs, and local rules change, always confirm current information with your utility providers and seek qualified professional advice for any personal tax or legal questions about energy incentives or billing disputes.
Q&A
What is a Household Bill Calendar, and how does it support a budget?
A Household Bill Calendar shows when income arrives and when recurring bills are due across the month. It helps you time payments and cash flow but does not replace a detailed budget for saving or long‑term plans.
How can I create a recurring bill list that captures all my payments?
Scan several months of bank and card statements and record every repeating charge, such as rent, utilities, insurance, phone, internet, memberships, and subscriptions. Note typical amounts, due dates, and payment methods in one organized file.
What is a simple way to organize billing accounts and login details?
Store company names, account numbers, websites, and support contacts in a secure tool like a password manager or locked folder. Having everything in one spot makes updating your calendar easier when providers change terms, rates, or schedules.
How can a monthly payment checklist help me track bills?
Use a checklist or calendar to mark when each bill is scheduled and when it is paid, whether by online transfer, check, or automatic debit. Lining this up with paydays shows tight weeks and reduces missed or duplicate payments.
How often should I review automatic payments and utility costs?
Check automatic withdrawals against your bill calendar at least once a month. Add short notes on utility bills to spot seasonal usage and rate changes, and seek qualified advice for tax or legal questions about fees or disputes.